Simple Budgeting Framework for Beginners
Everyone dreams of financial stability and the freedom it brings. Far too often, however, the journey feels overwhelming for many starting out. The world of personal finance is filled with complicated advice and complex charts.
If you find yourself anxious about money, uncertain about the future, or even embarrassed about how little you know—take heart. The path to financial empowerment is not reserved for experts.
In reality, a simple budgeting strategy can transform your relationship with money. This guide offers a practical, clear, and inspiring framework created specifically for beginners. Whether you’re a student, a new graduate, or simply looking to take charge of your finances, this article will equip you with the actionable steps and emotional encouragement you need.
Why Start with a Budget?
We have all felt the anxiety that comes from living paycheck to paycheck, or the sinking feeling after spending too much on little luxuries. A budget is not a punishment; it’s a tool for freedom. Building a budget is about creating a roadmap for your dreams, not restricting your joy.
With a simple budgeting framework, you gain clarity on where every dollar goes. You empower yourself to make choices. Most importantly, you start to see progress—slow at first, but always real.
Step 1: Track All Income
Before you plan where your money should go, it’s crucial to know how much is actually coming in. This means documenting every source of income you receive—salary, freelance payments, child support, side gigs, or even regular cash gifts.
Don’t estimate. Write down the exact amount you receive each month. Consistency is more important than perfection here. Create a simple list, a spreadsheet, or use budgeting apps—choose the format that feels easiest for you.
- Primary job take-home pay
- Part-time gigs and freelancing
- Alimony or child support
- Government assistance
- Other sources (like family help or passive income)
The goal is to create a complete picture of available resources. Once you see your numbers, anxiety subsides. You’re on your way to making conscious choices.
Step 2: List Your Expenses
Now, it’s time to shine a light on your spending. This step is absolutely vital, and it’s where many people discover surprising truths about their habits.
Spend a few minutes listing every single monthly expense—don’t leave anything out. Be honest. You’ll need to include both “fixed” (the same every month) and “variable” (amounts that change) expenses.
- Rent or mortgage
- Groceries
- Utilities (internet, phone, electricity)
- Insurance premiums
- Subscription services
- Coffee, eating out, entertainment
- Gas and transportation
- Debt payments (credit card, student loans)
For accuracy, look at your bank statements for the last two months. Patterns will emerge, showing you exactly where your money drifts.
Step 3: Establish Your Priorities and Goals
With income and expenses clear, pause to reflect on your aspirations. Every budget should align with what truly matters to you. Are you saving for a trip? Hoping to pay off debt? Dreaming of an emergency fund?
Pick one or two clear goals for now. Specificity is powerful: “Save $1000 in three months,” “Pay off $500 in credit card debt”. These concrete objectives keep you motivated and give your budget purpose far beyond numbers on a page.
Step 4: Plan and Allocate Your Money
Here’s where your budget becomes actionable. Compare your total income to your total expenses. Begin by allocating funds first to essential needs—housing, food, transportation, and non-negotiable bills.
Then, decide how much you’ll put toward your chosen goals. What’s left can flow into “wants”—movie nights, small treats, or personal hobbies.
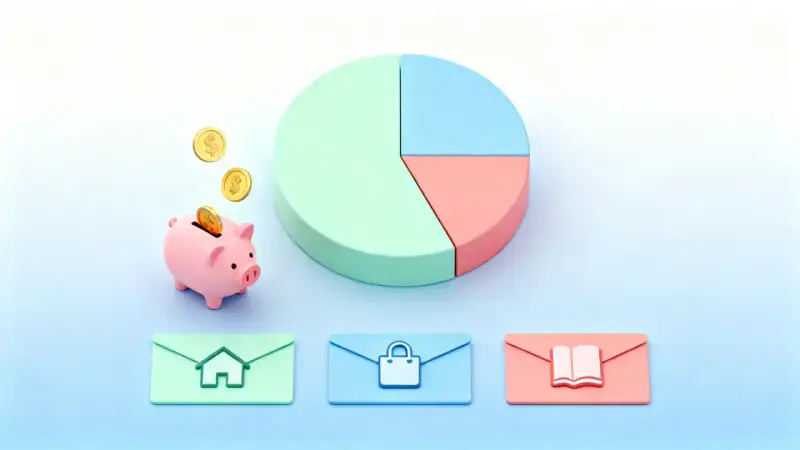
| Category | Recommendation (% of Income) |
|---|---|
| Needs (rent, bills, groceries) | 50% |
| Wants (entertainment, dining out) | 30% |
| Goals/Savings/Debt Repayment | 20% |
This classic split is just a starting point. If your situation doesn’t match, adjust it! The best budget fits your real life, not someone else’s expectations.
Step 5: Track, Review, and Adjust
The true magic of budgeting is not in strict adherence, but ongoing progress. Every month, review your spending. Did you stick to the plan? Did anything surprise you?
If you overspent on dining out, ask yourself why—then tweak next month’s plan. If you earned more from a side gig, celebrate and decide where that windfall should go. Small, regular adjustments keep your budget realistic and sustainable.
Remember: Progress over perfection. The goal is not to follow the plan to the letter, but to grow in awareness, intention, and self-control.
Overcoming Common Budgeting Challenges
Many people stumble at the first sign of difficulty. Life throws curveballs—a medical bill here, a car breakdown there. It’s easy to feel defeated, but these moments are exactly why a budget matters.
Here are some tips for overcoming common hurdles:
- Separate needs from wants: In moments of doubt, ask if a purchase is a genuine necessity.
- Create a small emergency fund: Even $500 can prevent a minor crisis from derailing your progress.
- Reward yourself for milestones: Celebrate progress—no matter how small—so the journey feels rewarding.
Final Thoughts: Embrace Your Journey
No matter where you are starting from, building a budget is an act of self-respect and hope. Financial discipline today creates the space for joy and generosity tomorrow.
As you move forward, remember that setbacks are normal. Some months will feel effortless, others will require courage and grit. What matters is your commitment to growth and your belief in a brighter financial future.
There’s power in simplicity. With this framework, you’re not just managing money—you’re reclaiming your story, dream by dream, dollar by dollar.