How to Prepare for Unexpected Expenses Before They Happen
Life has a way of throwing us curveballs when we least expect them. A car suddenly breaks down, a family member gets sick, or a natural disaster disrupts daily routines. In such moments, what stands between a minor inconvenience and financial turmoil is often how well we’ve prepared for the unexpected.
While no one can predict every twist that life will take, developing strategies to cushion these blows makes all the difference. Financial resilience is less about perfection and more about planning, persistence, and the courage to face uncertainty head-on.
Let’s explore practical, empowering steps you can take to prepare for unexpected expenses and ensure your peace of mind no matter what comes your way.
Recognizing the Inevitable: Unexpected Expenses are a Fact of Life
It’s easy to feel that planning for unknown expenses is unnecessary—until reality shifts. Maybe your reliable car needs a major repair, a medical bill arrives, or a household appliance quits without warning. The truth is, unexpected costs are part of life, and acknowledging this is the first step toward building true security.
When you accept that surprises will happen, you empower yourself to take action. Rather than being caught off guard and scrambling for solutions, you become the architect of your own safety net. This shift in mindset isn’t just practical—it’s transformative.
Practical Steps to Prepare for Unexpected Expenses
Achieving financial resilience doesn’t require perfection but consistent, proactive effort. Consider the following essential strategies to position yourself against life’s financial shocks:
- Start an emergency fund to cover at least three to six months’ worth of expenses. Even modest, regular contributions go a long way.
- Review and adjust your budget frequently. Make space for savings and anticipated irregular costs.
- Identify areas to cut back on unnecessary spending so more money can be freed up for emergencies.
- Understand and optimize your insurance coverage for home, health, and vehicle needs.
- Cultivate a proactive, positive attitude toward financial challenges—your mindset will be your greatest asset.
Let’s delve into each step with actionable ideas you can start applying today.
Building Your Emergency Fund: Your Financial Life Jacket
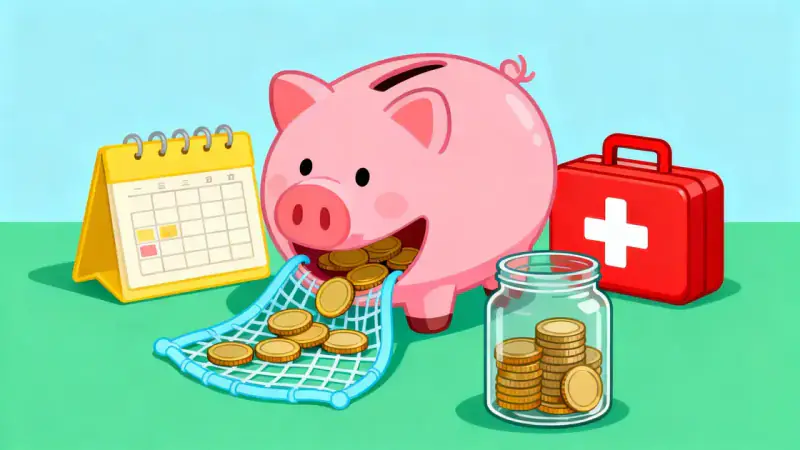
Few financial tools are more powerful than a dedicated emergency fund. This pool of money, set aside solely for unforeseen expenses, is your first line of defense against crisis. Even a small emergency fund can make the difference between managing a setback and spiraling into debt.
Start with a realistic goal—perhaps $500 or $1,000. Once the habit is established, steadily increase your target to cover several months of basic living costs, including rent or mortgage, utilities, food, and transportation. Consistency is more important than perfection, so set up automatic transfers to build your fund gradually. When emergencies strike, you’ll have the resources to weather the storm without panic.
Budget: The Blueprint for Financial Adaptability
A comprehensive, well-reviewed budget arms you with information and flexibility. Track your income and expenses closely, observe patterns, and distinguish between needs and wants. A detailed monthly budget helps highlight unnecessary outflows and uncovers opportunities to boost your savings rate.
To budget specifically for unexpected expenses, consider creating a “miscellaneous” category or allocating a fixed percentage of your income each month for the unexpected. This not only cushions the impact but also reinforces the discipline of saving.
Trimming Excess and Redirecting Resources
Most of us spend more on certain categories than we realize. Small recurring costs—a streaming subscription you barely use, dining out more often than planned, or impulse purchases—can add up over time. Redirecting even small amounts from nonessential spending to your emergency savings can have a dramatic long-term impact.
Here’s a useful exercise: Review your last three months’ worth of spending line by line. Identify expenses that didn’t add genuine value or utility, and redirect that amount straight into your emergency fund. Being intentional about your money now strengthens your resilience later.
- Audit subscriptions and memberships regularly.
- Shop with a list and avoid impulse buys.
- Commit to cooking at home more often.
- Negotiate or shop around for better deals on recurring expenses like cell phone plans and insurance.
Insurance: Protecting Yourself from Major Blows
Insurance isn’t the most glamorous topic, but it’s a pillar of financial protection. The right insurance acts as a safeguard against financially crippling, but relatively rare, disasters. Health, auto, homeowner’s or renter’s, and even life insurance policies can mean the difference between a manageable setback and long-term hardship.
Periodically review your insurance coverage and talk to trusted advisers about your needs. Don’t just shop for the lowest rate—ensure you understand your deductibles, coverage limits, and exclusions. When emergencies strike, you want to be certain you’re protected, not left battling fine print.
Mental Preparation: Building Emotional Resilience Around Finances
Financial resilience isn’t just about dollars and cents. How you think and react during a crisis is equally crucial. Develop the habit of staying calm and solution-focused. When an unexpected expense arrives, acknowledge the stress, then shift focus to the actionable steps you’ve already put in place. This empowers you to respond rather than react.
Education is essential too. The more you understand personal finance fundamentals, the more confident and poised you’ll be under pressure. Consider regularly reading, listening to finance podcasts, or attending workshops to enhance your knowledge.
Turning Preparation into Empowerment
Strengthening your defense against unexpected expenses is not about expecting the worst, but about creating peace of mind. Your future self will thank you for every dollar saved and every minute spent planning.
Unexpected costs are inevitable, but financial chaos doesn’t have to be. A structured approach—incorporating emergency savings, intentional budgeting, mindful spending, insurance, and emotional preparedness—creates a buffer between you and life’s volatility.
By taking proactive steps now, you ensure that when the next rainstorm comes, you’ll have your umbrella ready. Let this sense of preparedness empower you to live more freely, confidently, and generously every day.